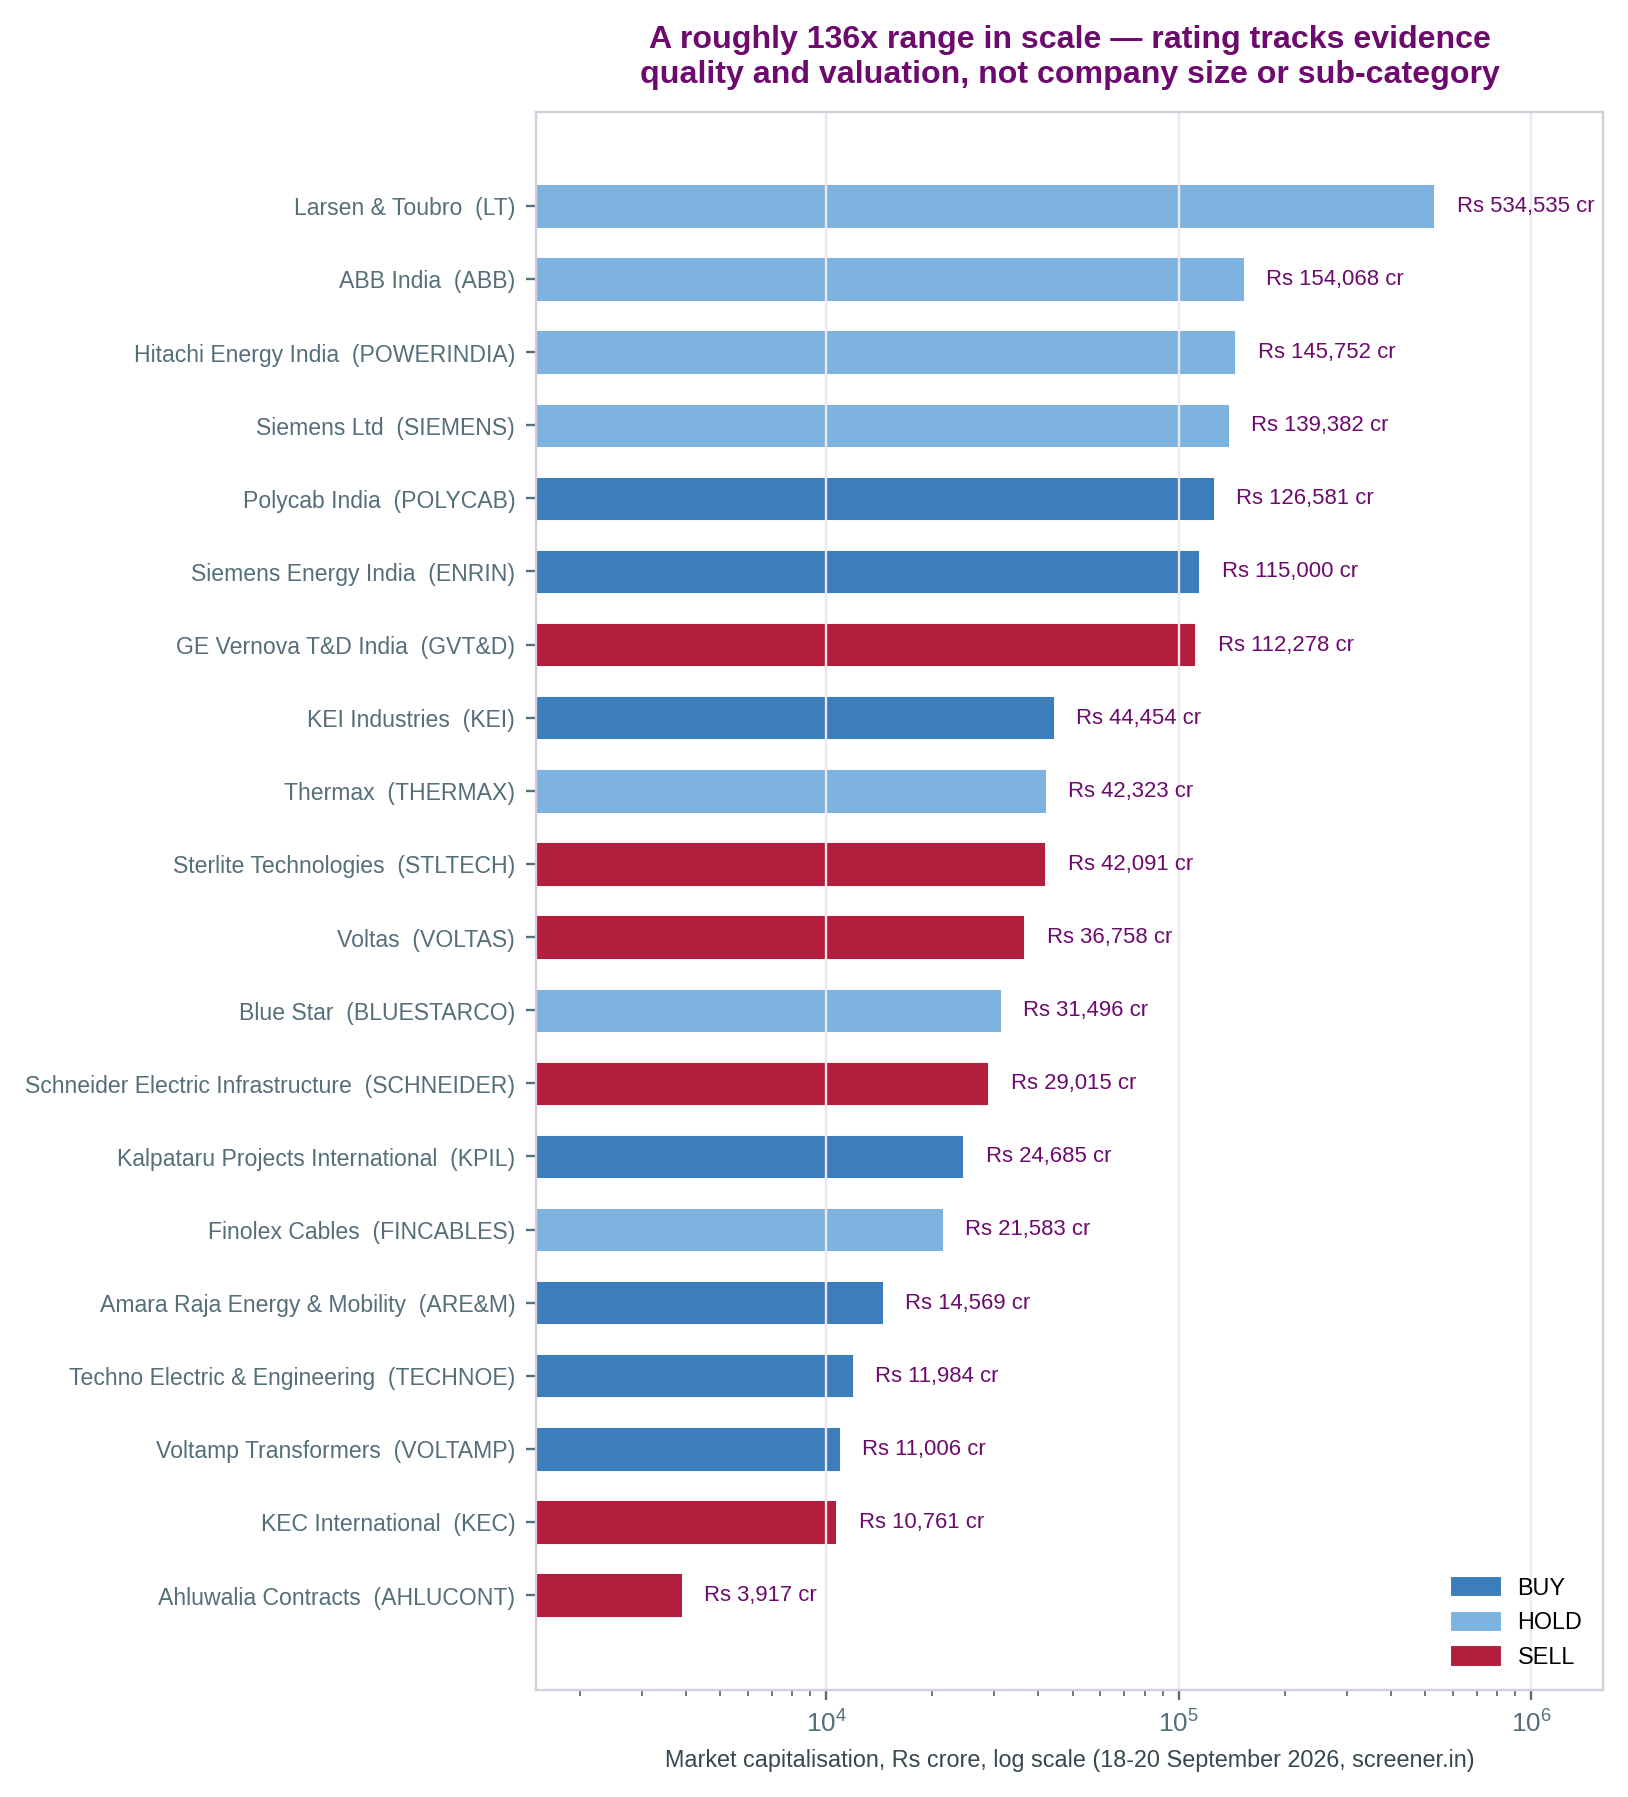
Twenty NSE/BSE-listed companies touch this value chain today, from a ₹5.3 lakh crore diversified construction-and-engineering conglomerate to a ₹3,900 crore pure construction contractor. They span every sub-category in §5 — power equipment, cabling, cooling, backup power and civil/EPC construction — and, as this report's own research repeatedly found, market capitalisation on its own tells you almost nothing about how much of a company's business is actually data-centre exposure, or how much of that exposure is management-confirmed versus purely thematic.
Splitting the twenty by how directly each company's own management — not sell-side analyst framing, not a website's list of served sectors — connects its growth to data-centre demand specifically produces a cleaner picture than either market cap or sub-category alone:
| Management-confirmed, quantified | Management-confirmed, not yet quantified | Thematic/analyst-level only |
|---|---|---|
| Voltamp Transformers — data centres were ~31% of Q1 FY27 order inflow, per company commentary | Siemens Energy India — a named TCS "HyperVault" AI-data-centre MoU, rupee value undisclosed | Polycab India — sell-side framing only ("Polycab, KEI likely beneficiaries"), no named contract |
| ABB India — signed hyperscaler "rate contracts" with disclosed differential pricing power | Blue Star — a dedicated, Uptime/TIA-942-compliant data-centre solutions group, but no disclosed DC-specific revenue figure | KEI Industries — management has quantified the sector-wide opportunity (₹25,000cr) but not its own DC-specific revenue |
| Sterlite Technologies — data centres grew from ~1% to ~21% of quarterly revenue in one year, backed by a named $1.1bn contract | Voltas — a ₹6,200+cr order book explicitly covering data centres, bundled with Metro/Tunnel work | Kalpataru Projects International — lists "data centres" as a served sector; no named contract found despite searching |
| Techno Electric & Engineering — a commissioned, named 36MW Chennai hyperscale facility | Hitachi Energy India — a public "30% of India DC spend" target, not yet a confirmed India-specific booked figure | Amara Raja Energy & Mobility — a real battery-storage business with no company-sourced statement tying it to AI/DC demand specifically |
| KEC International — one named, first-ever DC transmission project (Jul 2026), small but concrete | Thermax — one named 45,000 TR US hyperscale chiller order, unquantified as % of revenue | L&T — real (L&T-Vyoma) but ~1/100th of 1% of consolidated group revenue |
| Ahluwalia Contracts — two named contracts, both from 2022-23, stale | Siemens Ltd — automation/electrification angle, not a core DC play; separately, financials require reconciliation before any figure here should be trusted (§9 note below) | |
| GE Vernova T&D India, Schneider Electric Infrastructure, Finolex Cables — sector-beneficiary framing without a company-specific, named data-centre order |
Source: Dart Consultants, from each company's own report in this document (Part 4). Placement reflects the strongest DC-specific evidence found for each company, not its overall business quality — a company can be a strong business and still sit in the rightmost column (Polycab, KEI, Amara Raja all carry BUY ratings in §11 despite thematic-only DC evidence).
The leftmost column is not simply "the best stocks" — Sterlite Technologies sits there with a SELL rating (§11) because its best-quantified DC exposure in this entire report is wrapped in the least reliable earnings data of any company covered. The rightmost column is not simply "the worst stocks" — Polycab, KEI Industries and Amara Raja all carry BUY ratings built on business quality, with the data-centre angle as a genuine but secondary tailwind. Reading this table alongside §11's ratings, not instead of it, is the only way to use it correctly.
| Company | Ticker | Sub-category | Market cap |
|---|---|---|---|
| Larsen & Toubro | LT | Diversified conglomerate; civil/EPC construction | ₹5,34,535 cr |
| ABB India | ABB | Power equipment; electrification | ₹1,54,068 cr |
| Hitachi Energy India | POWERINDIA | Power equipment; transformers, switchgear | ₹1,45,752 cr |
| Siemens Ltd | SIEMENS | Automation; building electrification | ₹1,39,382 cr |
| Polycab India | POLYCAB | Cabling | ₹1,26,581 cr |
| GE Vernova T&D India | GVT&D | Power equipment; grid technology | ₹1,12,278 cr |
| Siemens Energy India | ENRIN | Power equipment; grid technology | ~₹1,15,000 cr |
| Thermax | THERMAX | Cooling; chillers | ₹42,323 cr |
| KEI Industries | KEI | Cabling | ₹44,454 cr |
| Sterlite Technologies | STLTECH | Cabling; optical fibre | ₹42,091 cr |
| Voltas | VOLTAS | Cooling; EMPS | ₹36,758 cr |
| Blue Star | BLUESTARCO | Cooling | ₹31,496 cr |
| Schneider Electric Infrastructure | SCHNEIDER | Power equipment; switchgear | ₹29,015 cr |
| Kalpataru Projects International | KPIL | Civil/EPC construction | ₹24,685 cr |
| Finolex Cables | FINCABLES | Cabling | ₹21,583 cr |
| Amara Raja Energy & Mobility | ARE&M | Backup power; batteries | ₹14,569 cr |
| Techno Electric & Engineering | TECHNOE | Civil/EPC construction; power | ₹11,984 cr |
| Voltamp Transformers | VOLTAMP | Power equipment; transformers | ₹11,006 cr |
| KEC International | KEC | Civil/EPC construction; T&D | ₹10,761 cr |
| Ahluwalia Contracts | AHLUCONT | Civil/EPC construction | ₹3,917 cr |
Sorted by market capitalisation. Source: screener.in and each company's own report in this document, 18-20 September 2026.
Schneider Electric Infrastructure Ltd (listed, switchgear/transformers only) is a different company from the unlisted Schneider Electric India Pvt Ltd, which houses the well-known APC/UPS data-centre brand and carries a CRISIL AAA/A1+ rating that belongs to that unlisted entity, not to these listed shares. Siemens Ltd and Siemens Energy India are two separate listed companies following a demerger effective 25 March 2025 — do not read one company's financials or history into the other's. Kalpataru Projects International is a distinct listed entity from the unlisted "Kalpataru Limited" real-estate arm under the same promoter family; a rating found for "Kalpataru" elsewhere may belong to that different entity. Siemens Energy India also shares no relationship with "SEIL Energy India Limited," an unrelated, Sembcorp-backed thermal-power company that happens to carry a similar name and its own CRISIL AA+ rating. Each of these distinctions is stated explicitly in the relevant company's own report; see them for the full detail.